
Direct answer: “ESG” is too broad to be a thesis topic on its own — you turn it into one by picking a specific reporting standard or disclosure practice (ISSB’s IFRS S1/S2, the EU’s CSRD/ESRS, or a voluntary framework like GRI or SASB), a specific accounting question about it (quality, comparability, assurance, or market reaction), and a specific method (disclosure content analysis, an event study, or a survey of preparers or auditors).
What exactly counts as “ESG” for an accounting thesis?
ESG reporting research in accounting is not about environmental science or corporate ethics in the abstract — it is about how firms measure, disclose and get assured on environmental, social and governance information, and how that information behaves like other accounting disclosures (subject to quality variation, managerial discretion, and market reaction). Naming the specific standard or framework you are studying is the first move that turns “ESG” from a buzzword into a researchable accounting object.
What is the current regulatory landscape you would situate the thesis in?
The IFRS Foundation’s International Sustainability Standards Board (ISSB) issued IFRS S1 (general sustainability-related disclosures) and IFRS S2 (climate-related disclosures, building on the TCFD framework) in 2023, and individual jurisdictions adopt them on their own timelines and in their own national versions. In parallel, the EU’s Corporate Sustainability Reporting Directive (CSRD) and its European Sustainability Reporting Standards (ESRS) have been under a simplification and timeline-adjustment process, so the in-scope companies and first reporting years have been shifting. Because this landscape moves quickly, state the specific standard, jurisdiction and effective date you are studying, and confirm each against the standard-setter’s or regulator’s own current page before you submit; a claim correct in one year can be outdated the next.
What’s a good problem statement built around ESG reporting?
Anchor the problem in a genuine tension, not just an observation that ESG reporting exists. A workable problem statement names a specific gap: for example, that voluntary ESG disclosure quality varies widely across firms adopting the same nominal framework, or that assurance on sustainability reports (limited versus reasonable assurance) has not kept pace with the assurance rigor applied to financial statements, or that the transition from voluntary frameworks (GRI, SASB) to mandatory ones (ISSB-based regimes, CSRD) creates comparability problems for firms and investors during the overlap period.
What objectives should the thesis state?
State objectives as concrete, measurable tasks tied to your problem, not restatements of the topic. For a disclosure-quality thesis: (1) build a disclosure index scoring compliance with a named standard’s specific requirements, (2) test which firm characteristics (size, industry, cross-listing status) predict higher disclosure quality, (3) assess whether disclosure quality is associated with an accounting or market outcome (cost of capital, analyst forecast accuracy, or assurance level obtained).
What theoretical framework fits an ESG accounting thesis?
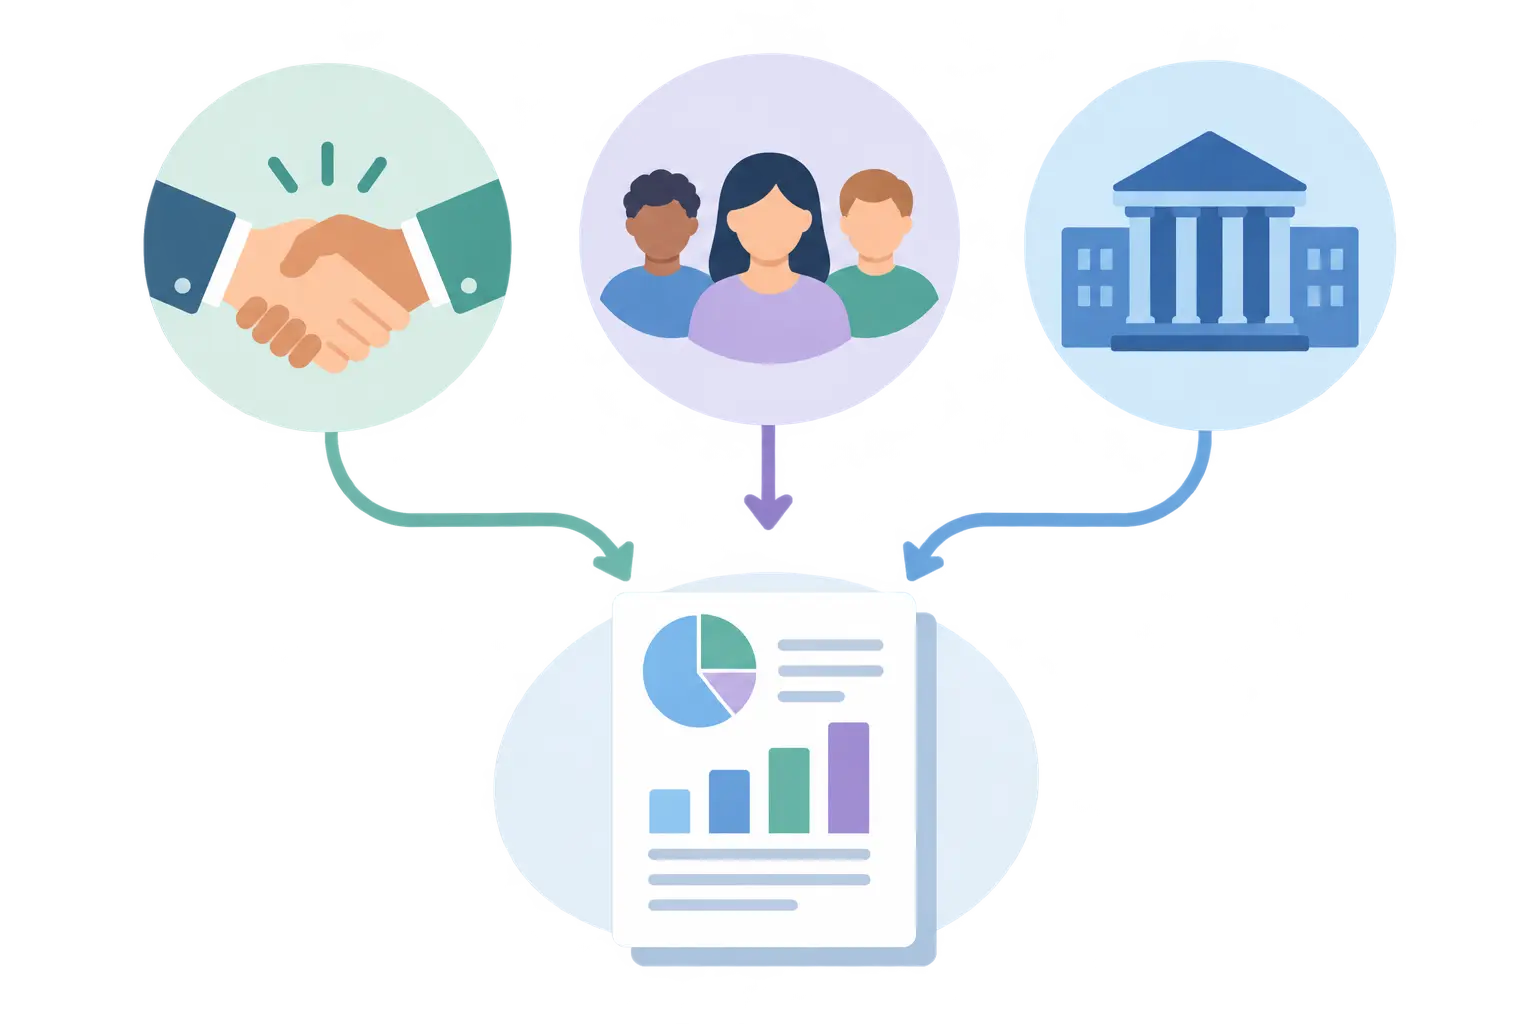
Three frameworks dominate this literature and are usually invoked to explain why firms disclose ESG information at all: legitimacy theory (firms disclose to maintain a social license to operate, especially after negative events), stakeholder theory (firms disclose to manage the information needs of stakeholders beyond shareholders), and institutional theory (firms disclose to conform to regulatory or normative pressure, explaining convergence toward common standards over time). Name which one your hypotheses actually predict from, since each implies a different pattern (legitimacy theory predicts disclosure spikes after scandals; institutional theory predicts convergence toward isomorphism across an industry).
What method should you use — content analysis, event study, or survey?
Match the method to the question. Disclosure content analysis (building a scored index against a standard’s specific line items) suits questions about disclosure quality, extent, or comparability. An event study (measuring abnormal stock returns around an ESG-relevant announcement, such as a compliance date or an ESG rating downgrade) suits questions about market reaction and value relevance. A survey of preparers or auditors suits questions about implementation cost, perceived assurance rigor, or professional judgement under a new standard, and is often the most tractable design for a thesis while the standards are still in transition and preparers have direct, timely experience to report on.
What data sources exist for ESG disclosure research?
- Company sustainability/ESG reports and annual reports filed with a regulator (SEC EDGAR, the UK’s Companies House, or the EU’s forthcoming European Single Access Point) — the primary source for a hand-coded or text-analysis-based disclosure index.
- Commercial ESG rating and data providers (Refinitiv, Bloomberg ESG, MSCI ESG Ratings, Sustainalytics) — commonly used as an independent, pre-scored measure of ESG performance or disclosure, though each provider’s methodology differs and ratings from different providers frequently disagree for the same firm, a well-documented “ratings divergence” problem worth naming explicitly if you use one. The general 40+ free datasets and open data repositories directory does not currently cover commercial ESG data providers, so budget for the fact that some of the sources above may require an institutional subscription rather than being freely downloadable.
- Academic ESG-specific databases such as the KLD/MSCI legacy database, widely used in older accounting and finance ESG studies for its long historical time series.
What are common weaknesses in ESG accounting theses?
The most frequent issues: treating “ESG” as one undifferentiated construct rather than separating the environmental, social and governance components (which often behave differently and are driven by different determinants); using a commercial ESG score without acknowledging or testing its known divergence from other providers’ scores for the same firms; and claiming a causal link between disclosure and a market outcome from a design that can only support an association. A related, subtler weakness is scope creep: starting with a tightly defined disclosure-quality question and drifting, mid-thesis, into broader claims about corporate sustainability performance that the accounting-disclosure data was never designed to support. Keep a one-sentence scope statement pinned above your draft and check every new paragraph against it.
How do you build a disclosure content-analysis index, step by step?
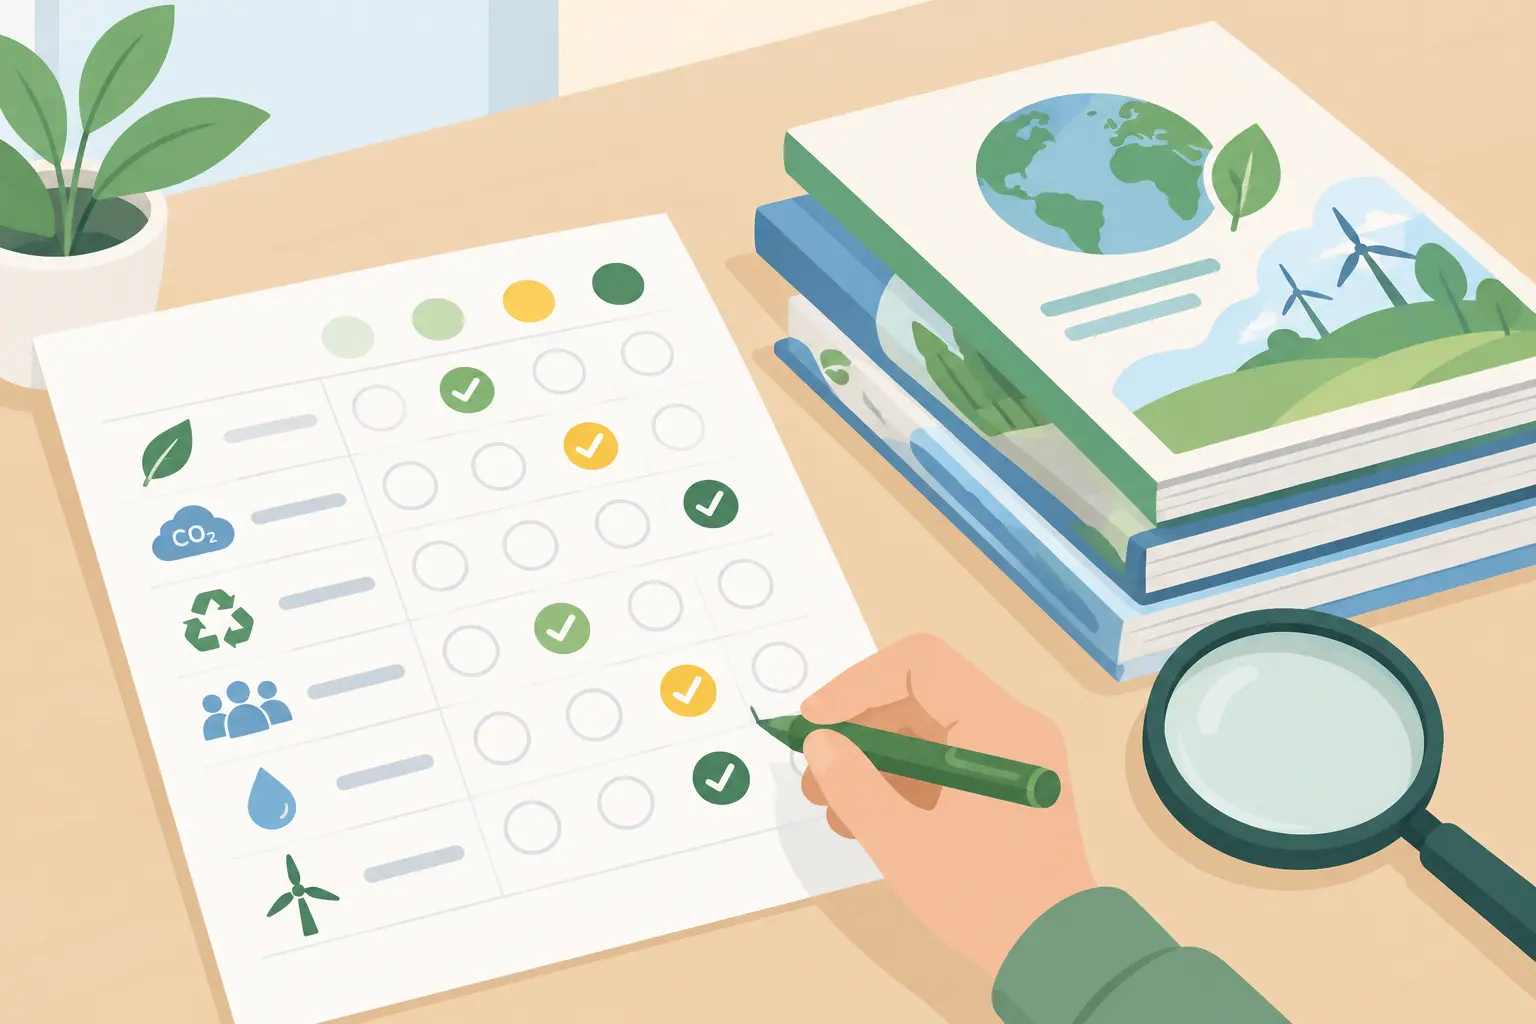
First, select the standard’s specific disclosure requirements (for example, IFRS S2’s required climate-related metrics and targets, or a named set of ESRS data points) and turn each requirement into a scoreable item — typically 0/1 for present/absent, or a 0–2 scale distinguishing a boilerplate mention from a substantive, quantified disclosure. Second, code a sample of reports (two independent coders for at least a subsample, reporting inter-coder agreement such as Cohen’s kappa) against every item. Third, aggregate item scores into a firm-level disclosure index, usually as a simple or weighted percentage of the maximum possible score. Fourth, validate the index against face criteria — a firm scoring near zero should visibly have thin, boilerplate disclosure when you read its report directly, not just a low number on paper.
What does a worked hypothesis set look like?
For a study on firm size and disclosure quality under a named standard: H1: Larger firms exhibit higher disclosure quality scores under the named standard, consistent with institutional theory’s prediction that larger, more visible firms face greater normative pressure to conform. H2: Firms newly brought into mandatory scope score lower in their first reporting year than firms with prior voluntary reporting experience under a predecessor framework (for example, prior GRI reporters transitioning to an ISSB-based regime). Each hypothesis should map onto a specific, nameable theoretical mechanism, not just an intuition that “bigger firms probably do better.”
How does an ESG accounting thesis differ from a general sustainability-management thesis?
A sustainability-management thesis in a business school might study whether ESG performance improves operational outcomes; an accounting thesis specifically studies the reporting, measurement, assurance and disclosure mechanics — the accounting-technical layer — which is a narrower and more tractable scope for a thesis-length project, and the framing your accounting committee will expect to see.
Where does this fit with the wider accounting dissertation structure?
The theoretical framework and method choices above slot into the same chapter structure any accounting or business dissertation follows — see how to write a business management dissertation for the full chapter-by-chapter guide this topic sits inside, and which theoretical framework a business or management dissertation should use for how legitimacy, stakeholder and institutional theory compare to the other frameworks business committees commonly see.
Where does Tesify fit?
Once you have picked your standard, your theoretical lens and your method, Tesify’s thesis workspace, used by 9,000+ students and 15,000+ chapters, helps you structure the problem statement and objectives. Every word stays 100% written by you, and Tesify cannot tell you which ESG standard is currently in force in your jurisdiction, so check that regulatory detail against a primary source before you submit.
Frequently asked questions
Is “ESG accounting” a real, recognized sub-field?
Yes — sustainability accounting and reporting is an active, growing stream within accounting research, published in mainstream accounting journals, distinct from corporate social responsibility research in management schools.
Do I need a finance background to do an event-study design?
Basic familiarity with market-model abnormal-return estimation is necessary, but accounting programmes that teach capital markets research typically cover this; it is learnable within a thesis timeline if you start early and use standard event-study software or packages.
Can I study a single company’s ESG reporting as a case study?
Yes, particularly for a qualitative or exploratory design examining how a company’s disclosure changed under a new standard, though a single-firm case study should be explicit about its limited generalizability compared to a cross-sectional design, and named in your methods chapter against Robert Yin’s case-study design criteria (case boundaries, unit of analysis, and the logic linking evidence to your propositions) rather than left as an unstructured description. A single-case design can still be rigorous if you triangulate multiple years of the same firm’s reports against interview data from its sustainability or investor-relations team, rather than relying on the published reports alone.
Should I use GRI, SASB, TCFD or ISSB standards as my reference framework?
Pick whichever framework is legally or normatively binding on your sample firms during your study period — using ISSB as the reference for a sample of firms not yet required to report under it, for example, risks scoring firms against requirements that did not yet formally apply to them.
How do I handle ESG ratings disagreement between providers?
Either pick one provider and justify why, or use multiple providers explicitly as a robustness check and report where results are, and are not, consistent across them — silently picking whichever provider supports your hypothesis is a methodological red flag.
Is greenwashing a good angle for an accounting thesis?
Yes, if operationalized narrowly and measurably — for example, as a gap between disclosed environmental claims and third-party-verified performance data — rather than as an unmeasurable accusation about corporate intent.
What sample size does a disclosure content-analysis thesis typically need?
There is no fixed minimum; a cross-sectional index study needs enough firms for meaningful statistical comparison across your predictor variables, and you should justify the number against your industry and comparison groups, while a smaller, more deeply coded sample can still support a qualitative or case-based design.
Can I study assurance (auditor sign-off) rather than disclosure content itself?
Yes — comparing which firms obtain limited versus reasonable assurance on sustainability reports, which assurance provider they use (a Big Four accounting firm versus a specialist sustainability assurance provider), and whether assurance level is associated with disclosure quality is a well-established and distinct accounting research question from disclosure content itself.
How do I justify the time period my sample covers?
Tie the window explicitly to a regulatory milestone — the year a standard became mandatory in your jurisdiction, the year a predecessor voluntary framework was phased out, or a specific fiscal-year cutoff — rather than an arbitrary “last five years” convenience window, since reviewers will ask what regulatory event, if any, your period brackets.
What if my chosen standard changes or is amended while I am writing?
State the version and date of the standard you coded against explicitly in your methods chapter, and if a material amendment is announced before your defence, add a short note acknowledging it rather than silently updating your analysis — sustainability standards are unusually fast-moving right now, and committees are aware of this.
Write your thesis with AI
Structure, draft, cite, and format your thesis faster with Tesify’s AI writing tools, automatic bibliography, and plagiarism checker. Free to start, no credit card required.

Leave a Reply